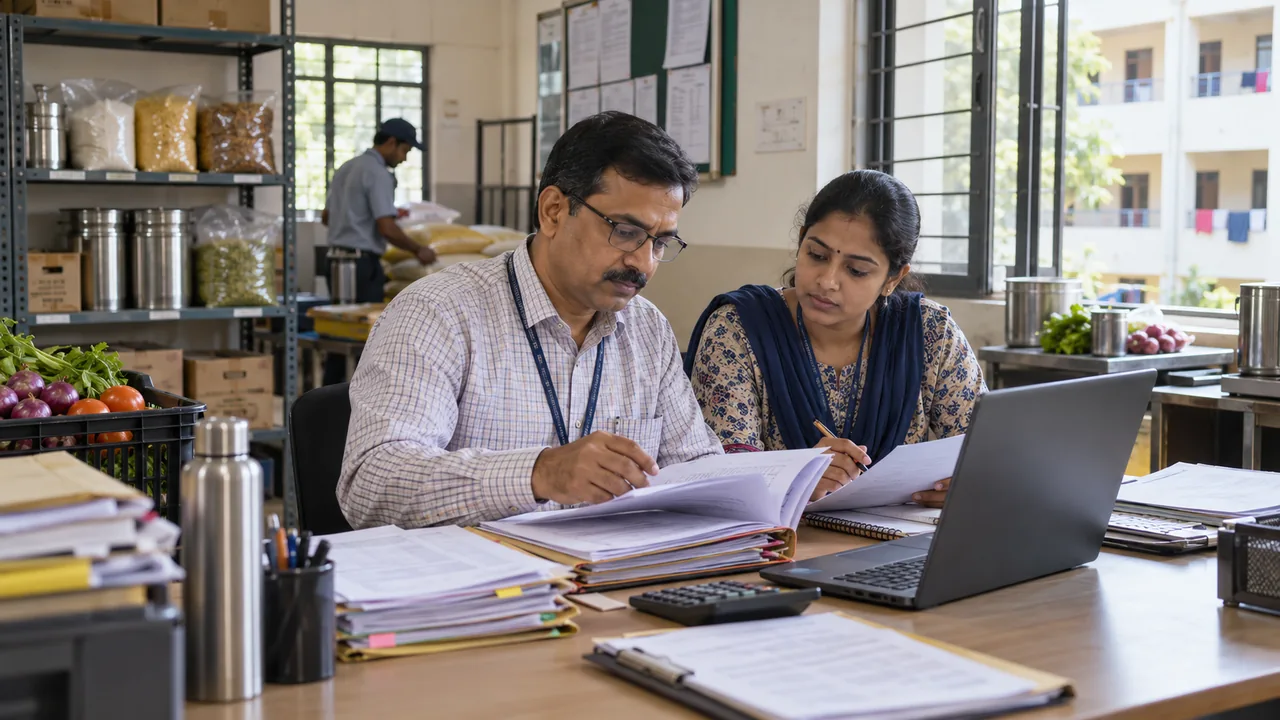
Financial leakage is reduced by separating request, approval, receipt and payment; reconciling independent records; and reviewing unusual exceptions—not by adding signatures that nobody verifies.
Hostel and mess operations combine high transaction volume with decentralised receipt of goods and services. Leakage may arise from error, weak design, collusion, duplicate work, unrecorded inventory, informal collections or refunds that remain unresolved. Controls should protect public or institutional money without delaying essential resident services.
Map the complete money and material flow
For each major spend or collection, map request, approval, order, receipt, issue, consumption, invoice, payment and reconciliation. Name the record and owner at each step. A control gap usually appears where one person can create, approve and confirm the same transaction.
Separate incompatible responsibilities
- The requester should not be the sole approver.
- The person confirming receipt should not create the vendor invoice record.
- Inventory issue and stock verification should be independently reviewed.
- Resident damage assessment should have evidence and an appeal route.
- Refund preparation and payment approval should be separated and reconciled.
Control hostel fees, deposits and refunds
Publish charge rules, due dates and exception authority. Generate receipts through approved systems, prohibit informal personal-account collections and reconcile resident, finance and bank records. Track refunds by ageing and reason; a refund is not closed when approved, but when credited or otherwise lawfully resolved and communicated.
Strengthen mess and inventory controls
- Use approved specifications, units and vendor terms.
- Record receipt quantity, quality exceptions, lot or batch information where relevant and the receiving officer.
- Compare meals planned, produced and served with occupancy-adjusted consumption and waste.
- Investigate repeated emergency purchases, round-number consumption, unexplained yield change and stock adjustment.
- Physically verify selected high-value or fast-moving items without relying only on the same ledger.
Verify vendor bills against service evidence
Match the purchase or work order, evidence of receipt, service records, agreed rates, applicable deductions and invoice. For manpower contracts, reconcile authorised deployment, attendance evidence, duty coverage and statutory documentation through qualified finance and labour-compliance review.
Use exception analytics
- Duplicate invoice numbers, values or bank details.
- Frequent orders just below an approval threshold.
- Unusual weekend or holiday transactions.
- Repeated single-source or emergency procurement.
- High damage charges, waivers or manual adjustments by location or user.
- Vendor concentration and repeated quality acceptance despite complaints.
Protect reporting and investigation
Provide a confidential route for staff and students to report suspected irregularity. Preserve records, restrict allegations to need-to-know review and avoid public accusation before fair investigation. Correct the process weakness even where individual misconduct is not established.
Conclusion
Good financial control is visible in reliable services, explainable charges and traceable decisions. The aim is not paperwork for its own sake, but confidence that money and materials reached their intended purpose.
- Department of Expenditure: procurement manuals, including current goods, works and services editions
- Manual for Procurement of Goods, Second Edition 2024
- Implementation note: public, private, deemed and state universities may follow different finance, tax, labour and procurement rules; obtain qualified review.
- Department of Expenditure General Financial Rules updated to 31 January 2026
- Department of Expenditure Procurement Policy Division
Revision history
Editorial language, consistency and source audit completed. India-specific operating context retained.
See something we should improve?
Point out a correction, add a missing perspective or share a stronger source.